Before the Client Speaks: A Disciplined Read of Public Company Records
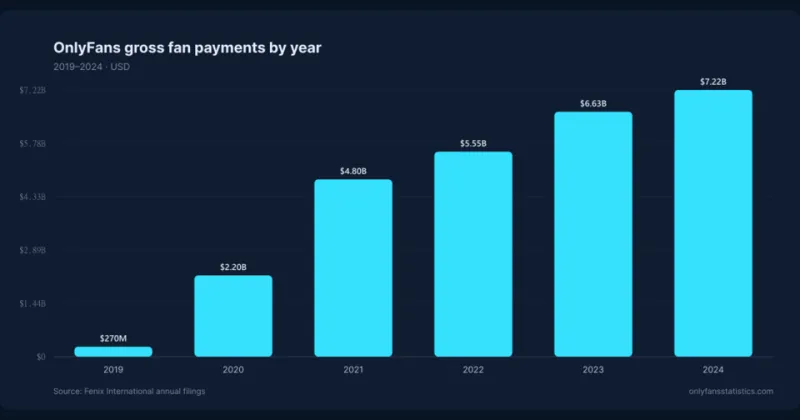
Photo: OnlyFansStatsEditor, CC BY-SA 4.0, via Wikimedia Commons
A client meeting rarely begins when the room fills. It begins earlier, in the quiet interval when a director's appointment has just been filed, a strategic report has been published, or a charge has been registered. These are not secrets. They are public records, available to anyone who takes the trouble to read them. Yet in the routine of pitching, reviewing and renegotiating, they are often overlooked in favour of the internal deck, the remembered conversation or the assumption that the relationship already supplies enough context.
The argument here is not that public filings provide a crystal ball. They do not. They are lagging, partial and occasionally bland by design. The argument is that they provide something more useful than prediction: a disciplined way to form better questions before a client says a word.
The record is a map, not a verdict
Companies House is the obvious starting point, but it is not a single document. It is a set of signals. The confirmation statement establishes the basics. The register of persons with significant control begins to show where influence sits. Director appointments and resignations, particularly when they cluster, can indicate a shift in executive priority or a change in the composition of the board. Charges registered against the company may reveal secured lending arrangements that shape how cautiously a finance director will approach new commitments. Insolvency history, where it exists, is a matter of record rather than gossip.
None of these facts should be treated as conclusions. A new finance director does not automatically mean a tighter budget. A registered charge does not automatically mean constrained cash. But each is a legitimate prompt. If a client has recently changed its company secretary or added a non-executive director with a particular specialism, it is reasonable to ask how decision-making is evolving. If a charge has been satisfied, it is reasonable to wonder what that says about the refinancing cycle. The discipline lies in moving from observation to question, not from observation to clever assumption.
Read the narrative for what it avoids
The strategic report, where one is published, is often more revealing for its omissions than its assertions. UK company law requires certain disclosures, but it does not require a company to be interesting. Many reports are exercises in cautious wording. That is precisely why changes in wording matter. A shift from confident language about expansion to more guarded language about market conditions is a signal. A sudden emphasis on cost discipline, supply chain resilience or liquidity is worth noting. So is the disappearance of a metric that previously appeared every year.
The same applies to the accounts themselves. For larger entities, the notes may show movements in trade creditors, debtor days, intercompany balances or dividend payments. For smaller companies, the filed accounts may be abridged or exemption-based, which limits what can be inferred. That limitation is important. A thin filing is not evidence of a thin business. It is evidence that the public record is thin, and the briefing should say so plainly rather than fill the gap with speculation.
Three steps from document to dialogue
The first step is to establish the entity. Before reading any numbers, confirm the legal name, company number, group structure and the identity of the people with significant control. Check whether the client you are meeting is the same entity that files the accounts. In group structures, the trading company and the holding company may tell different stories. This step prevents the common error of briefing a partner on the wrong balance sheet.
The second step is to read for change over time. A single year's filing is a snapshot. Two or three filings begin to show a trajectory. Director churn, movements in charges, changes in accounting reference dates, the appearance or disappearance of subsidiaries, and shifts in the language of the strategic report all become more meaningful when read in sequence. The aim is not to build a case. It is to identify two or three areas where the public record suggests something has moved.
The third step is to convert those areas into neutral questions. Not: 'Your accounts suggest you are under pressure.' Rather: 'I noticed the last filed accounts showed a change in the composition of the board. Is there anything about the decision-making structure we should account for in our proposal?' Not: 'Your strategic report sounds cautious.' Rather: 'The most recent report placed more emphasis on cost control than previous years. Would it be helpful to frame our scope around efficiency as well as delivery?' The question should be answerable, respectful and clearly grounded in a public document. It should also leave room for the client to say the filing does not tell the whole story, because it usually does not.
A one-page brief is enough
The output of this exercise should be short. A single page with three sections is sufficient: what the public record shows, what it does not show, and the questions it raises. That page should be shared with colleagues before the meeting, not used as a script during it. Its purpose is to improve listening, not to demonstrate research. A client who senses that you have read their filings carefully will often volunteer context that no public document contains.
The habit also has a commercial benefit. It reduces the risk of arriving with a generic pitch at the very moment a client is wrestling with a specific structural or financial question. It makes the difference between a supplier who has done background reading and an adviser who has understood the shape of the organisation.
The limits are part of the discipline
Public filings are not a substitute for the conversation. They are a preparation for it. They are filed late, sometimes abbreviated, and always written with an eye on audience. A director's departure may be routine. A cautious strategic report may be boilerplate. The disciplined reader holds those possibilities open rather than reaching for the most dramatic interpretation.
That restraint is what separates a briefing from a rumour. The client may confirm the signal, correct it or ignore it. All three outcomes are useful. What matters is that the meeting begins with a better question than it otherwise would have. In a relationship-driven market, that is a quiet advantage: the public record, read carefully, makes room for a more informed conversation.